
Demand Drivers:
Demand Constraints:
Supply Constraints:
September provided a strong demand signal which indicates that global demand has continued to absorb elevated pricing better than initially anticipated. The accelerated receipt pace should continue to be interpreted cautiously given unique harvest dynamics. Greater clarity on final volumes and crop composition should emerge as harvest approaches completion. Attention will begin to shift toward replenishment activity following Diwali, US-China trade relations, European coverage for first half of calendar 2027, and the market’s ability to maintain the current sales pace. Overall supply and demand fundamentals continue to support a stable-to-firming outlook.
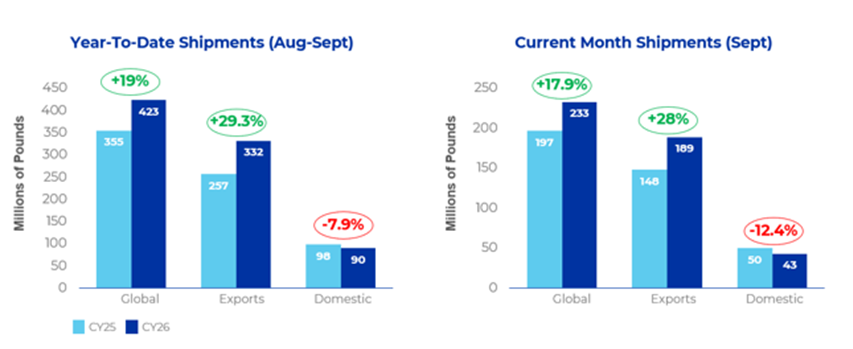
For the second month of this crop year, shipments exceeded industry expectations surpassing prior year by double digits. September shipments totaled 232.5 million pounds. Exports reached 189.2 million pounds, an increase of 28%, while the domestic market shipped 43.4 million pounds, a decline of -12.4% versus last year. Despite challenges in the domestic market, total shipments continue to outperform prior year by 19%, driven by strength in export markets.
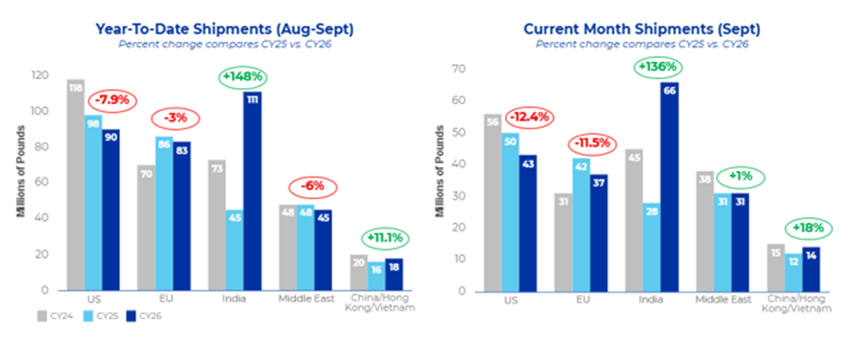
India remained the clear demand leader in September, with shipments of 66.4 million pounds compared with 28.1 million pounds last year, an increase of approximately 136%. Year-to-date shipments have reached 110.6 million pounds compared with 44.5 million pounds last year, an increase of approximately 148%. The pace reflects strong purchasing activity ahead of the festival season and California’s continued importance as India’s primary source of inshell almonds. With significant volume now arriving in destination markets, local inventory movement and post-festival replenishment will become increasingly important indicators of demand over the coming months. Many buyers will continue to watch transit times, as some vessels that were supposed to arrive before the festival season have been delayed.
Direct shipments to China/Hong Kong improved to approximately 2.9 million pounds, more than double last September, while year-to-date shipments are approximately 32% ahead of prior year. Vietnam received 11.4 million pounds during September and remains modestly ahead year to date. Other destinations within the region were less consistent. Regional trade flows remain fluid as buyers position around potential changes in U.S.-China trade policy. Recent discussions have resulted in new framework aimed at providing more favorable tariffs for select agricultural products. Market participants increasingly expect tariff relief on U.S. almonds beginning in January. Further progress could improve the longer-term trade environment and potentially support more direct shipments to mainland China.
European shipments totaled approximately 37.4 million pounds in September, down roughly 12% from prior year. Year-to-date volume stands at approximately 83.3 million pounds, down about 3%. Western European markets showed mixed performance. Germany, Italy and the United Kingdom remain ahead year to date, while Spain and several other markets have softened. Buyers continue to seek coverage, but purchasing remains disciplined as customers manage higher prices and alternative-origin availability and price advantages.
Middle East shipments totaled approximately 31.3 million pounds in September, essentially in line with prior year. Year-to-date shipments stand at 45.5 million pounds, down approximately 6%. Turkey continued to perform strongly, with September shipments reaching 13.2 million pounds and year-to-date volume up approximately 61%. Saudi Arabia also strengthened, while UAE shipments remain significantly below prior year. Pakistan has emerged as a significant growth destination this season. However, a new customs valuation ruling effective in October increased the assessable value of shelled almonds to $3.81/kg, potentially raising landed costs and creating some uncertainty around the sustainability of recent import growth. These shifts continue to illustrate changing regional trade flows and inventory channels across the Middle East and South/Central Asia rather than a uniform change in end market consumption.
September domestic almond shipments totaled 43.3 million pounds, down 12.4% year over year. Domestic demand continues to lag expectations, with September marking the second consecutive month of year-over-year shipment declines. New domestic sales also fell 23% compared to September 2025, reflecting continued caution among buyers. Entering the 2026/27 crop year, there was optimism that the domestic market had turned a corner, with expectations for more stable shipment volumes and consistent purchasing activity. While the first two months have fallen short of those expectations, current commitments provide a foundation for potentially steady shipments throughout the calendar year. Buyers are expected to remain disciplined in their purchasing strategies layering in coverage as needed rather than aggressively extending positions. Looking ahead, domestic market activity will center on shipments supporting holiday production schedules and retail sales programs.
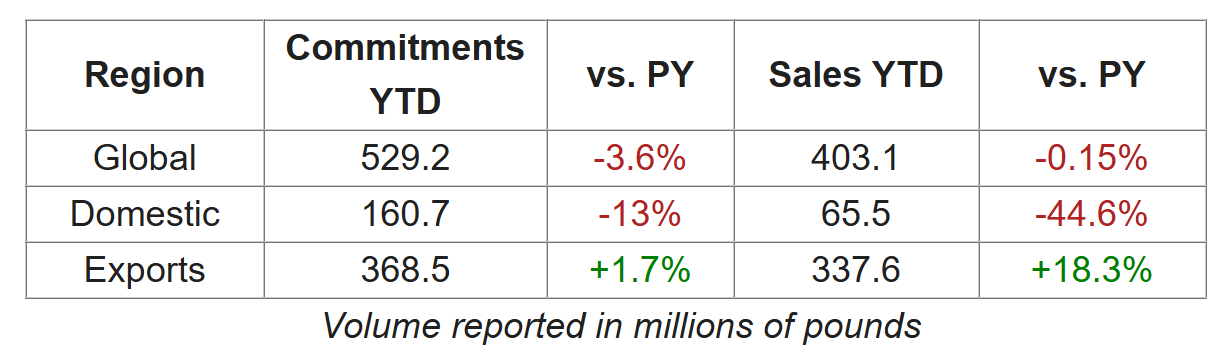
Total committed shipments stand at 529.2 million pounds, tracking -3.6% behind prior year, largely driven by reduced sales in the Domestic market. New sales for September were up 20% at 264.3 million pounds, driven by exports which are currently tracking ahead of prior year by 1.2%. For the month of September exports added 215.3 million pounds of coverage (up 37.8% from PY) while Domestic added 49 million pounds (down 22.6% from PY).
Skepticism about crop size remains a factor as many are focused on near in demand instead of long-term contracts given price risk. Receipts coming in earlier and at a faster pace have resulted in uncommitted inventory being up by 157 million pounds at 709 million pounds total for now. The table below shows commitments and sales in both domestic and export markets.
2026 crop receipts to date total 1.2 billion pounds, running 22.5% ahead of the same point in 2025. As noted in previous Market Reports, the 2026 crop is 1-2 weeks ahead of 2025, reflected in September crop receipts. The post-bloom heat accelerated crop development and had other implications such as smaller kernel sizes, driving a lower-than-expected crop. Growers have all but wrapped up orchard harvest, and attention has shifted to post-harvest activities. Huller-sheller pacing was also accelerated this year due to favorable orchard and weather conditions. Huller-shellers are focused on running stockpiles, largely pollinizer varieties. Many huller-shellers have already wrapped up running for the year and most are projected to complete late November/early December.
Current receipts show smaller kernel sizes across all varieties, and lower moisture content versus 2025, all putting downward pressure on kernel weight, and ultimately crop potential. As noted last month, Nonpareil and Independence yields varied by region and reflect a lower Nonpareil and higher Independence crop. Pollinizers have come in lower than expected, driven largely by weak performance in Butte/Padre and California varieties.

Senior Sales Director Nut Ingredients

Senior Key Account Manager Global Partner